All Categories
Featured
Optimising Operational ROI through Advanced Market Research
Will Market Analytics Drive Middle East Corporate Success?
How Does Business Excellence Essential for 2026 Growth?
Table of Contents
The sector also faced broader macro headwinds, including a more mindful policy background in China and international risk-off sentiment driven by geopolitical tensions and higher energy costs. Thematic ETFs Had a hard time for the most part, especially those linked to carbon and high-growth technology, as appraisal pressures and global rate characteristics weighed on efficiency.
The petrochemical ETF substantially surpassed. Circulations in Q1 2026 were modest and extremely focused, reflecting selective allocation instead of broad market involvement. Regardless of weak efficiency, ETFs tape-recorded $27.1 million in net inflows, with just a small number of products drawing in brand-new capital. This shows that financiers were targeting particular exposures, while lowering or turning out of others.
Trading activity remained constant, with average 30-day volumes around 33,000 shares, focused in a handful of larger and more liquid ETFs. Most activity appears to have taken location in the secondary market, making it possible for investors to adjust positions without substantial primary creations or redemptions. While recent geopolitical events have actually resulted in more monetary pressure on GCC countries, the area stays resistant and well capitalized to deal with the circumstance.
In January, Boreas launched its S&P Global Luxury UCITS ETF, adding a specific niche thematic exposure focused on global high-end and consumer brands. Momentum continued into April with the approval of KraneShares AGIX and KWIN ETFs by the CMA for cross-listing on ADX. These funds are expected to introduce in April pending a last approval from ADX.
Q1 2026 showed some development relating to ETFs in the GCC. We expect more international and thematic ETFs to list in the GCC throughout 2026. While the dispute has affected belief and costs during the quarter, it has actually driven more volume and interest in regional assets.
Strategic Strategy for Regional Leadership
In spite of continuous geopolitical stress and security threats throughout the Middle East, the economies of the Gulf Cooperation Council (GCC) have actually continued to demonstrate resilience, preserving favorable growth momentum in the last few years. While conflicts in the larger area and global economic uncertainty stay a structural restriction, GCC countries have actually up until now limited their influence on domestic economic efficiency through strong financial positions, policy continuity, and sustained financial investment.
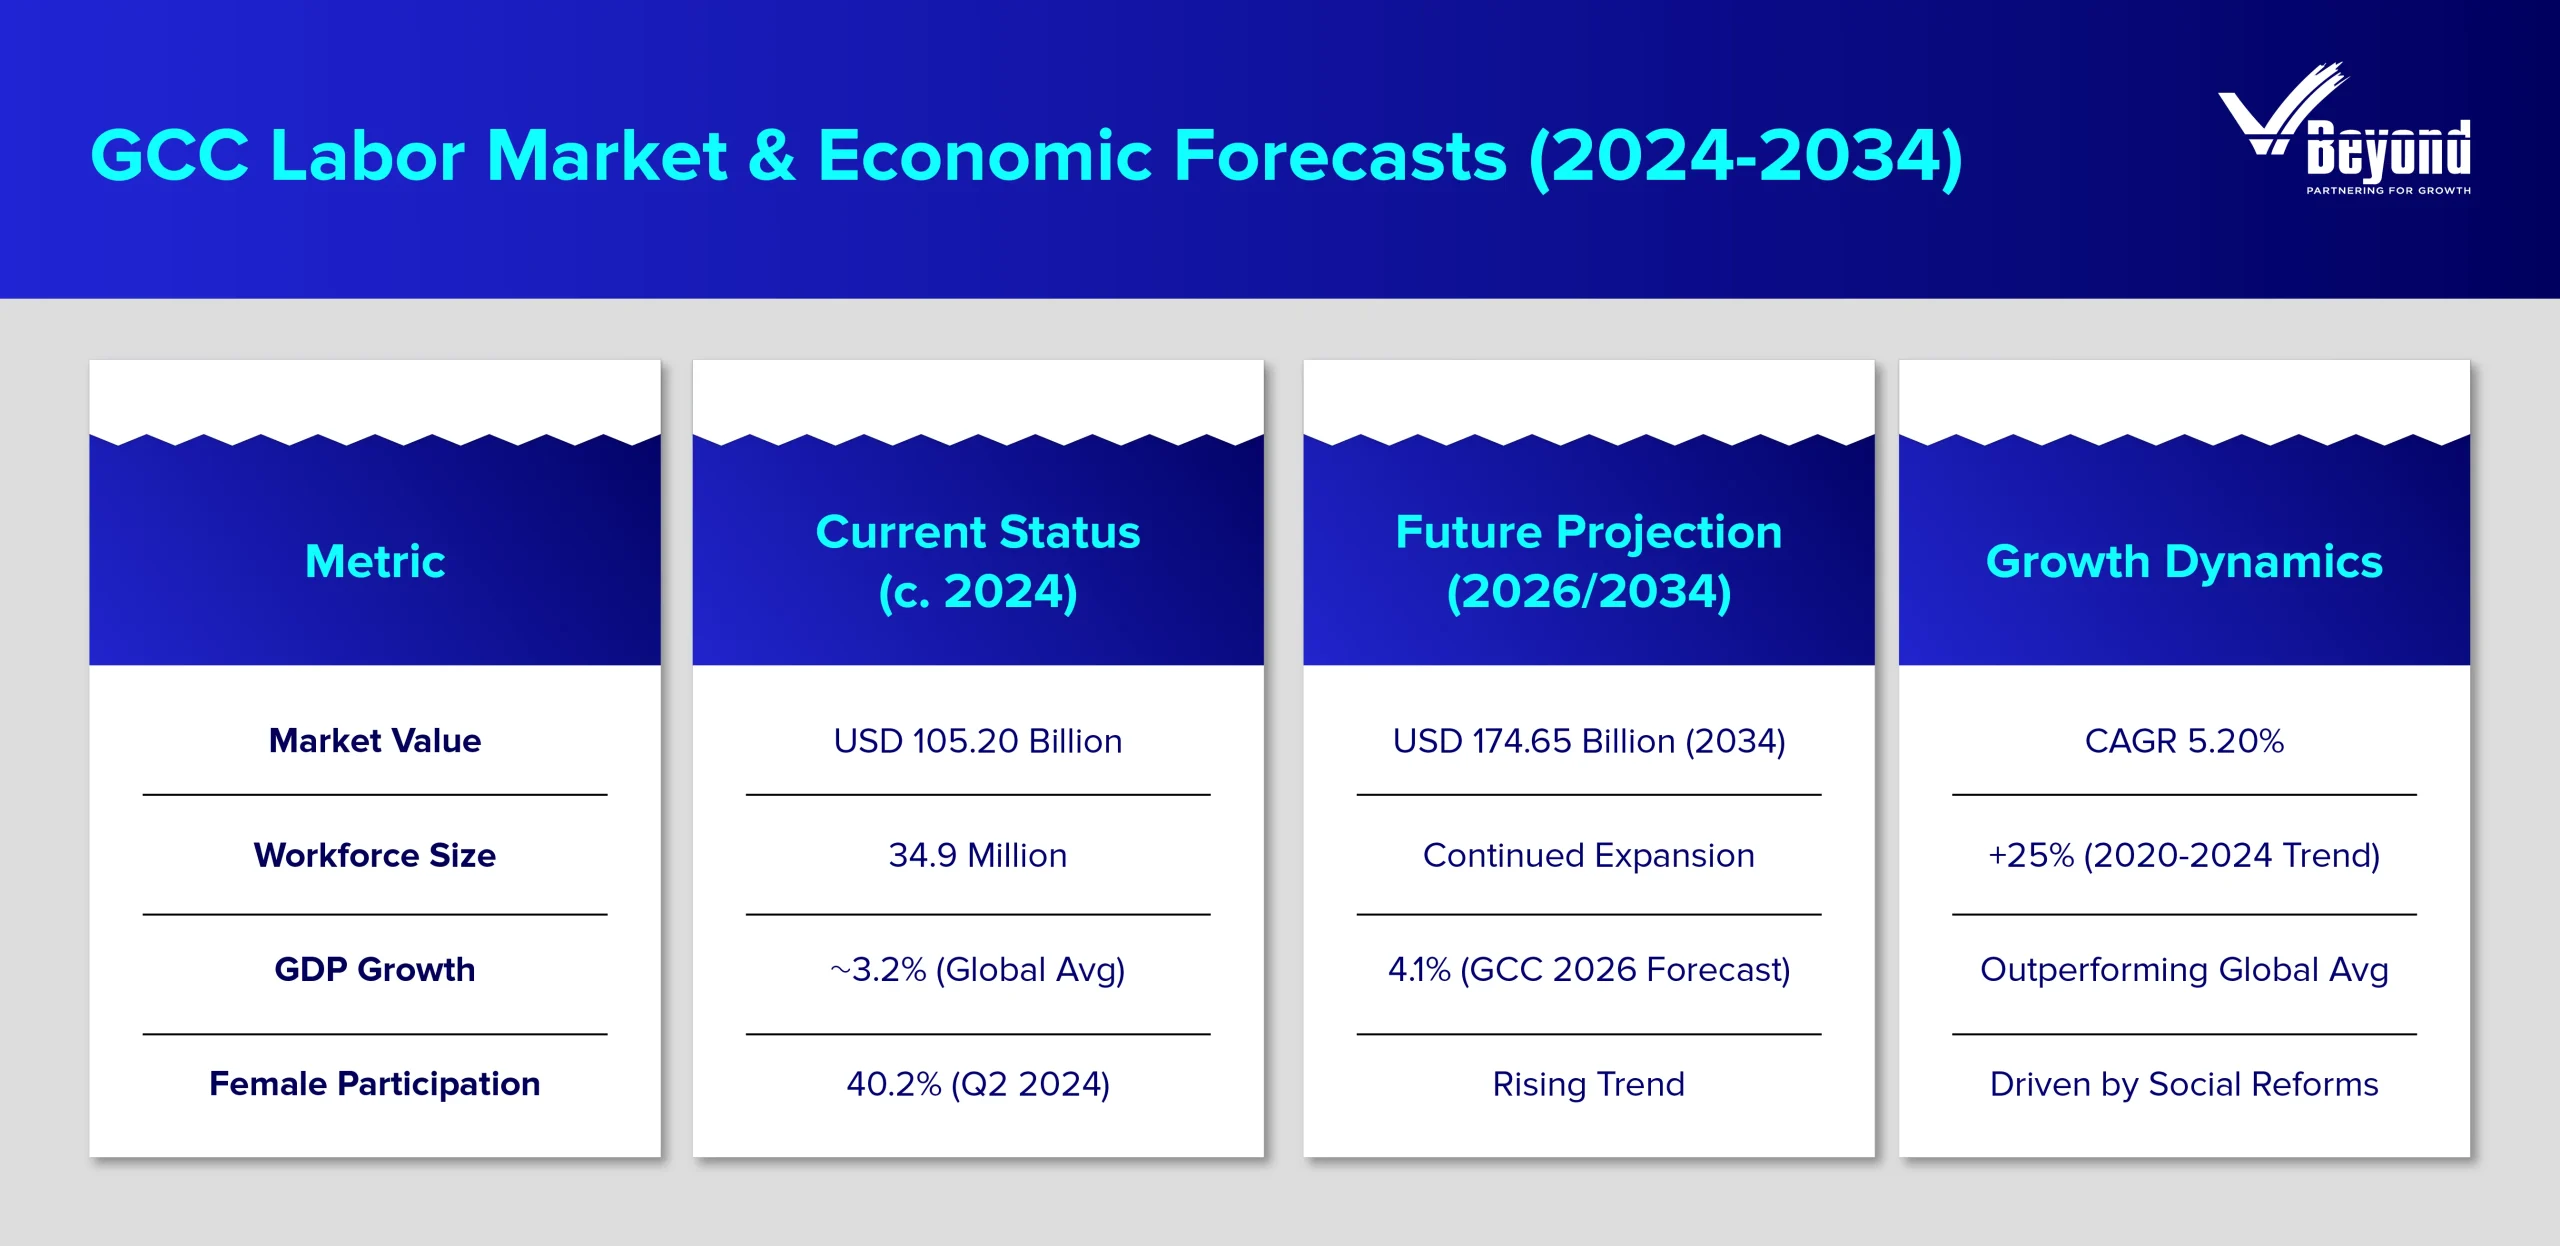
The World Bank, on the other hand, jobs 3.2 percent growth in 2025, speeding up to 4.5 percent in 2026. The IMF similarly sees momentum improving, with GCC output growth predicted to increase from 1.7 percent in 2024 to 3.3 percent typically in 2025, reflecting a shift toward more favorable total conditions.
Mapping GCC Market Strategy for 2026The IMF's World Economic Outlook (October 2025) projects global development easing to 3.1 percent in 2026, with innovative economies around 1.5 percent and emerging market and developing economies simply above 4 percent. On that contrast, a 4.44.5 percent GCC expansion would position the area materially ahead of the world average and slightly above (or broadly in line with) the emerging-market aggregate, strengthening the GCC's status as a fairly high-growth pocketprovided that local risk conditions remain included and reform momentum holds.
How Is Business Excellence Crucial for Future Expansion?
Information from the GCC Statistical Center show that non-oil sectors currently account for more than 73 percent of overall GDP, a share that has continued to rise as federal governments broaden financial investment in services, facilities, and technology. According to Oxford Economics, non-energy activity across the GCC is projected to grow by around 4.1 percent in 2026, supported by strong labor markets, improving credit conditions, and rising financial investment in technology and AI-related infrastructure.
Public-sector investment and reform remain main to sustaining this trend. Policy procedures focused on bring in foreign direct investment, easing foreign ownership rules, broadening capital markets, and supporting private-sector involvement continue to underpin non-oil growth and decrease the region's exposure to oil price volatility. While hydrocarbons no longer dominate the growth outlook, oil revenues are expected to play an encouraging function in 2026.
3.2 percent growth in 2025, speeding up to 4.5 percent in 2026. Sees momentum improving, with GCC output growth predicted to increase from 1.7 percent in 2024 to 3.3 percent on average in 2025, showing a shift toward more favorable total conditions.
The IMF's World Economic Outlook (October 2025) jobs international development reducing to 3.1 percent in 2026, with innovative economies around 1.5 percent and emerging market and developing economies simply above 4 percent. On that contrast, a 4.44.5 percent GCC expansion would place the area materially ahead of the world average and a little above (or broadly in line with) the emerging-market aggregate, enhancing the GCC's status as a fairly high-growth pocketprovided that regional threat conditions remain contained and reform momentum holds.
How Is Operational Excellence Crucial for Future Expansion?
Data from the GCC Statistical Center reveal that non-oil sectors already represent more than 73 percent of overall GDP, a share that has actually continued to rise as governments expand investment in services, infrastructure, and technology. According to Oxford Economics, non-energy activity throughout the GCC is projected to grow by around 4.1 percent in 2026, supported by strong labor markets, enhancing credit conditions, and increasing financial investment in innovation and AI-related facilities.
Maximising Operational Efficiency through Advanced Market PlanningPublic-sector financial investment and reform stay main to sustaining this pattern. Policy steps focused on bring in foreign direct investment, reducing foreign ownership rules, expanding capital markets, and supporting private-sector involvement continue to underpin non-oil expansion and lower the region's exposure to oil rate volatility. While hydrocarbons no longer dominate the development outlook, oil profits are anticipated to play an encouraging role in 2026.

Latest Posts
Why Does Business Excellence Vital for Future Growth?

Optimising Operational ROI through Advanced Market Research
Ways to Enhance GCC Corporate Strategy